“Income tax returns are the most imaginative fiction being written today.”
~ Herman Wouk

The government has never been particularly shy about taking credit for other people’s productivity. But there’s a difference between taxing what you make and taxing what’s left after you’ve paid the bills. (Source: Doug Casey’s Crisis Investing)
Note from Addison: If you’ve been following along with Grey Swan, you know through our investment recommendations and sponsored webinars, we routinely advocate the basics: “buy low, sell high” … “never lose money”…. “It’s not how much you make, it’s how much you keep.” Tangential to those fraternity goals, today our buddy John Hunt extols the capital benefits of being self-employed…
The IRS taxes a small business owner or 1099 contractor on his profits.
It taxes an employee on what he is paid.
The employee doesn’t get to deduct from his taxable income the expenses of driving to work. The small business owner gets to deduct driving to a client, a worksite, or to the bank. The employee doesn’t get to deduct his tools, his education, his office, the utilities he consumes, his internet, his computer. The 1099 contractor does.
One way to legally avoid taxes is to set yourself up to be taxed on what you keep instead of what you are paid.
Profit Is the Point
Many of us work all the time at making a profit. Be it a practice, a consultancy, a rental, or a vineyard, the purpose is the same. I run a farm winery in Virginia. Pruning vines in February is absolutely not a hobby for me. I don’t even drink.
When the aim is profit, every dollar spent earning it should come off the top before anyone taxes the result. Profit and loss is the signal that tells a producer whether he is serving customers or wasting his capital and labor. A tax on revenue scrambles that signal.
The tax code agrees, but primarily for one class of worker. Section 162 lets the self-employed deduct the “ordinary and necessary” expenses of carrying on a trade or business. Schedule C is where that happens: receipts at the top, expenses below, tax on the profits. For farmers, there is a Schedule F, which has various tax advantages too.
The employee gets no such treatment. Congress suspended the deduction for unreimbursed employee expenses beginning in 2018, in a law President Donald Trump signed. The employee’s unreimbursed personal expenses for tools, home office, mileage, professional dues and continuing education come out of his after-tax pocket.
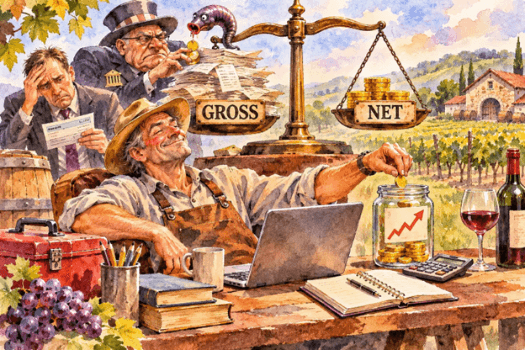
The employee is taxed on gross. The 1099 contractor is taxed on net.
What the self-employed are allowed to deduct
The list is wonderfully long. I’m a pediatrician, not a tax advisor (thank God), so get better advice from tax-savvy people. Consider the below to be entertainment, not advice. Entertainment, because it is fun to learn legal ways to avoid paying the blood-sucking leeches.
You can deduct ordinary expenses. Software, phone, internet, insurance, professional fees, advertising, supplies, subscriptions and business travel, and a lot more. The employee can’t do any of that.
Home office. Deduct a share of your home costs for space used regularly and exclusively for your business. I myself exclusively work. I don’t play. My office is large, my workshop facilities that I use to generate profit are large. The expenses of them are deductible. Beware, the IRS might choose to scrutinize a home office deduction. Never forget that government guns are big and powerful. They rob what they choose to rob, and call you the criminal if you hide a ten-dollar bill in your sock.
Travel and Vehicle. Business travel is deductible. For your car, the IRS set 72.5 cents per business mile for 2026, then raised it to 76 cents on July 1 because of fuel prices. Keep a mileage log so that if the IRS comes at you, you have your proof.
Equipment. One hundred percent bonus depreciation is permanent for qualifying property acquired after January 19, 2025, and Section 179 expensing runs to $2.56 million in 2026. Deduct the machine in the year you put it in service. Section 179 cannot exceed your business income. Bonus depreciation, however, can push you into a loss that you can use against other income.
Retirement. A Solo 401(k) lets a self-employed person put $24,500 into a Roth account in 2026. At 50 or older, add $8,000. At ages 60 to 63, add $11,250 instead. You pay the income tax now, but everything in the account comes out tax-free in retirement. A Roth IRA tops out at $7,500 and shuts out high earners.
Medical Insurance. On a Schedule C, you can deduct 100 percent of health, dental and long-term-care premiums above the line up to your net profit. You can also fund a Health Savings Account. HSAs are wonderful. But the insurance you need to qualify for them has become terribly expensive since the Affordable Care Act came along to make things unaffordable.
The 20 percent deduction. Section 199A lets you deduct up to 20 percent of qualified business income (QBI). There are all sorts of little qualifiers on what qualifies and what doesn’t and various limits here and there (including for physicians, lawyers, consultants and others), so read the fine print.
Your children. Wages a sole proprietor pays his own child under 18 are exempt from Social Security and Medicare tax. A child with no other income can earn up to the standard deduction, $16,100 in 2026, without owing income tax. The work must be real, the pay reasonable, the records kept. Again, I’m no tax advisor, so dig into this on your own.
Timing. Cash-basis bookkeeping provides some (limited) flexibility to defer income into next year, pull expenses into this one and offset other income with a business loss.
But the self-employed pay double the payroll tax, don’t they?
A W-2 employee sees 7.65 percent of pay withheld for Social Security and Medicare. The employer pays another 7.65 percent that never appears on the paystub. Of course, the employer budgets the total cost of your labor (including his half of the damn payroll tax, unemployment tax, etc.) and pays you the remainder. The money the government forces the employer to pay could be the employee’s money if the government weren’t taking it. The burden of taxes is always, in the end, paid not by companies, but by We the People.
When the self-employed pay both halves (the “self-employment tax”) to fund the socialist programs known as Social Security and Medicare, the combined rate is 15.3 percent applied to 92.35 percent of their net self-employment earnings, up to the Social Security wage limit (Medicare tax continues beyond any limit). It is no worse than what the employee is losing from his paycheck.
Medical Insurance, Forced or Otherwise
Medical insurance is the widest gap, and the question is who gets to choose. The employee takes the plan HR selected at the price HR negotiated. The premium is deducted from the company’s taxable income, and not added to the employee’s taxable income or payroll tax base. This tax scheme for employer-paid medical insurance is what created the whole employer-based “health care” insanity that infects the USA.
The self-employed person chooses the plan and the deductible, pays the whole premium, deducts it from income tax, but still owes 15.3 percent on the money (because the deduction does not reach self-employment tax). On tax treatment alone, the employee wins over the self-employed here.
Compulsion is the worse arrangement on either side. Obama signed the individual mandate in 2010. The federal penalty has been zero since 2019, though some states still charge one. Personally, I skip insurance altogether. Instead my family and I participate in voluntary medical cost sharing or crowd-funding programs, which are so much cheaper than insurance that the tax break for insurance becomes a rounding error. They aren’t health insurance, but then, these days, neither is health insurance.
Where a self-employed person loses
No employer. No retirement match, no paid leave, no group disability policy, no one to share the risk. No boss. No one to sue if you are fired and feel the need to blame others. The self-employed person needs to do the extra tax work, which is burdensome. But if you think of that work as time spent keeping your earnings for yourself instead of having it extracted by blood-sucking leeches, then the tax work can be fun.
The hobby trap. Section 183 presumes a profit motive if you show a profit in three of five years. Without that record, the IRS weighs nine factors, and if it calls your business a hobby, the income stays taxable while the expenses disappear. The Treasury’s inspector general for tax administration has pressed the IRS to pursue Schedule C businesses with repeated losses. Keep a business plan, a separate bank account, books and a mileage log. Make sure your businesses are profitable sooner rather than later. Otherwise, you may be wasting your capital and labor. If you have a hobby and want to treat it like a business, make it a real business, not a joke of a business. Seek the profit.
Liability. A sole proprietor is personally liable. A single-member LLC helps with the liability concern (presuming you don’t commingle funds, carry adequate liability insurance, aren’t negligent, don’t commit malpractice and don’t make personal guarantees), but is disregarded for tax purposes. The LLC’s expenses are filed on your Schedule C. A multi-member LLC is taxed as a partnership instead: a separate return, a K-1 for each member, and no Schedule C.
Recapture and benefits. If you deduct the full $60,000 cost of a truck in year one and later sell it for more than its adjusted tax basis, the gain may be taxed as ordinary income through depreciation recapture. Every deduction also lowers the earnings record Social Security uses to compute your “benefit.”
The next rung. Once profit is high, an S corporation election can cut self-employment tax by paying you a reasonable salary and the rest as distributions. It adds payroll, a second return and scrutiny of the salary. Ask your CPA where the break-even sits.
Summary
If you are a hardworking US taxpayer, producing more than you consume, saving the rest, trying to generate a profit instead of parasitizing off society, and want to legally keep more of your hard-earned gains, then there are few better ways to do it than to be self-employed and filing a Schedule C (or a Schedule F for farmers).
~ John Hunt, MD
Doug Casey’s Crisis Investing & Grey Swan
P.S. The foundation of money is changing again.
First it was gold, then oil, and now it’s compute. Six of the biggest names on Wall Street have committed $500 billion to it.
When money moves like this, the people who get positioned first usually come out ahead.